FIRB Eligible
FIRB eligibility confirmed by the listing agent.63 Lilley Street, Hendra
An Inspired Expression of Design and Sustainable Luxury
6 Bedrooms4 Bathrooms2 Cars407 m²
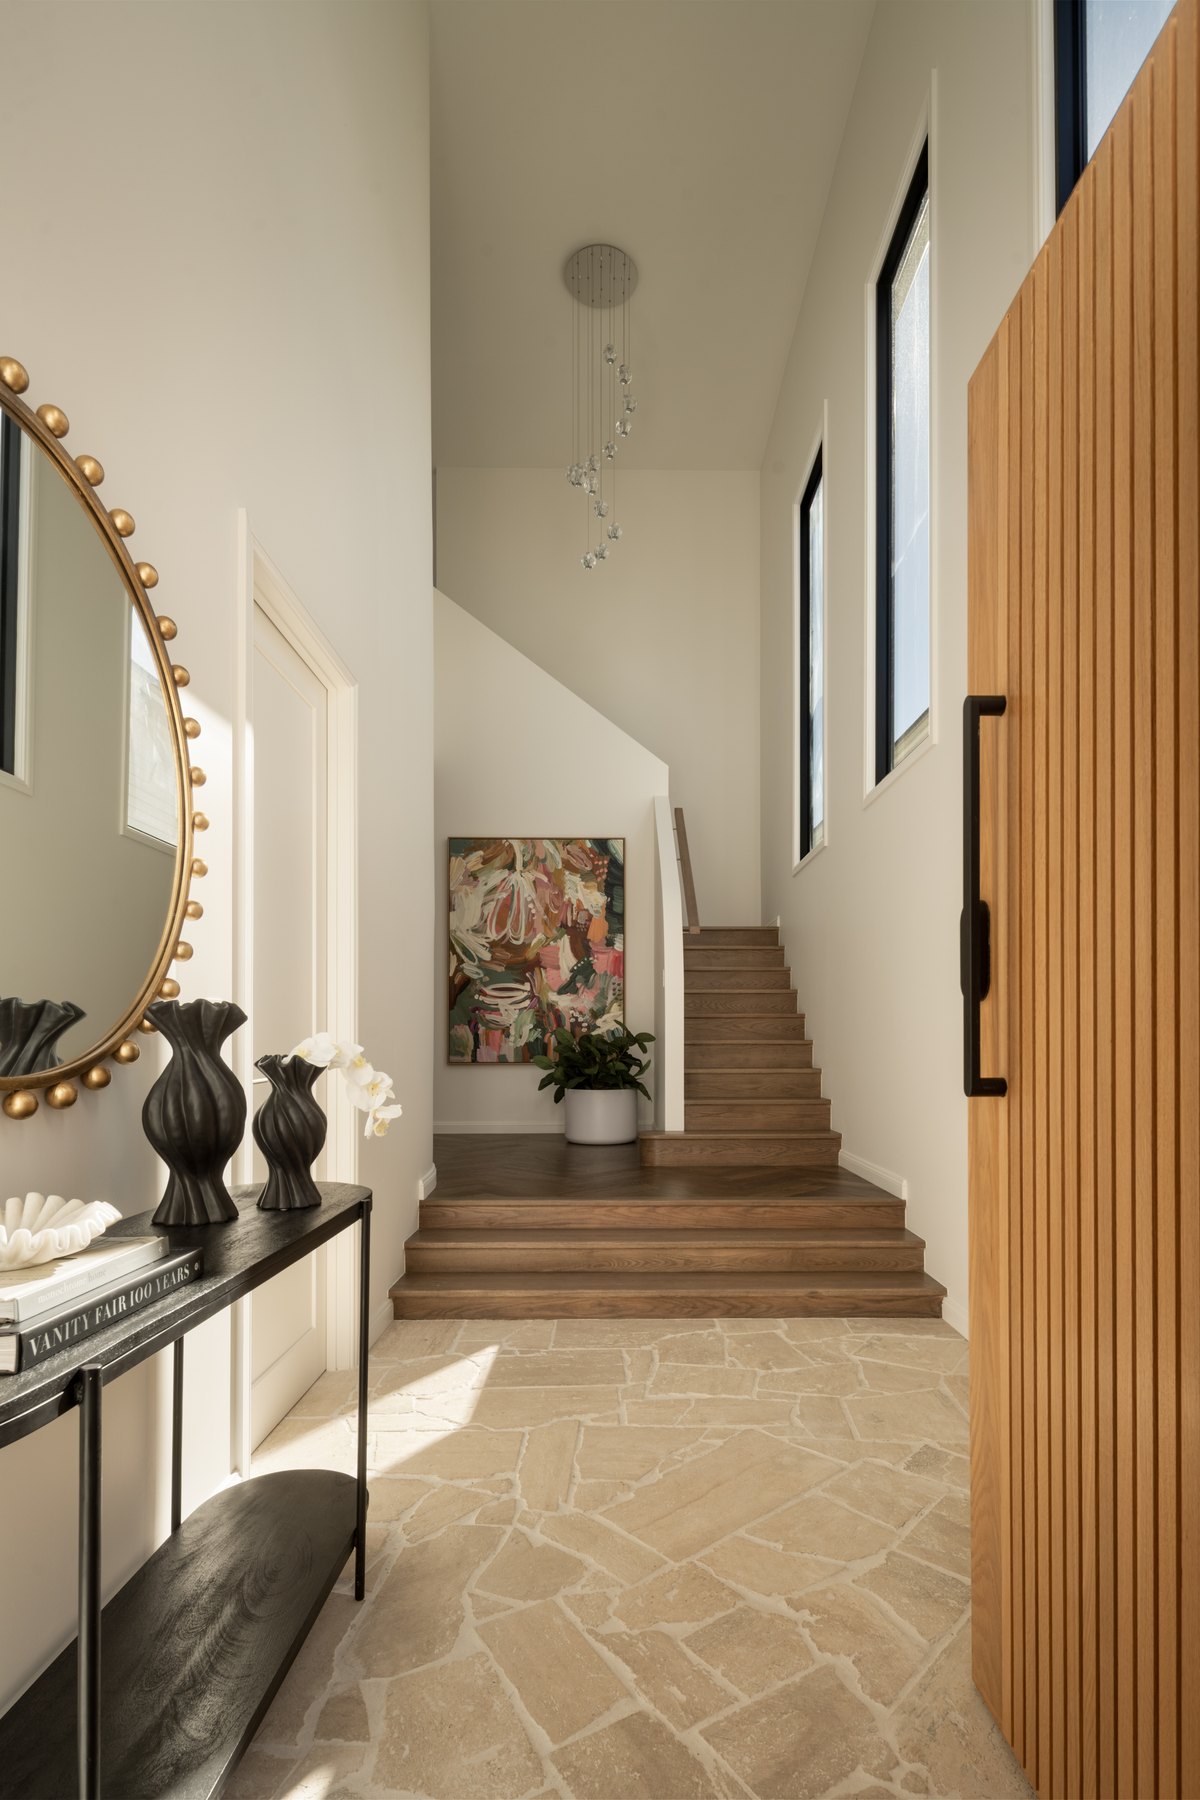
“Lily on Lilley” is a newly completed residence combining refined contemporary design with a seven-star energy rating, extensive solar and battery capacity, a saltwater pool and flexible family living. Positioned about 8 km from Brisbane’s CBD, it offers convenient access to Racecourse Village, Brisbane Airport, renowned schools and local transport.
Property details and image sourced from Ray White Clayfield. Buyers should confirm current availability and particulars with the listing agent. Foreign buyers must obtain any approval required for their individual circumstances before purchase.